

This Week in 30 Seconds
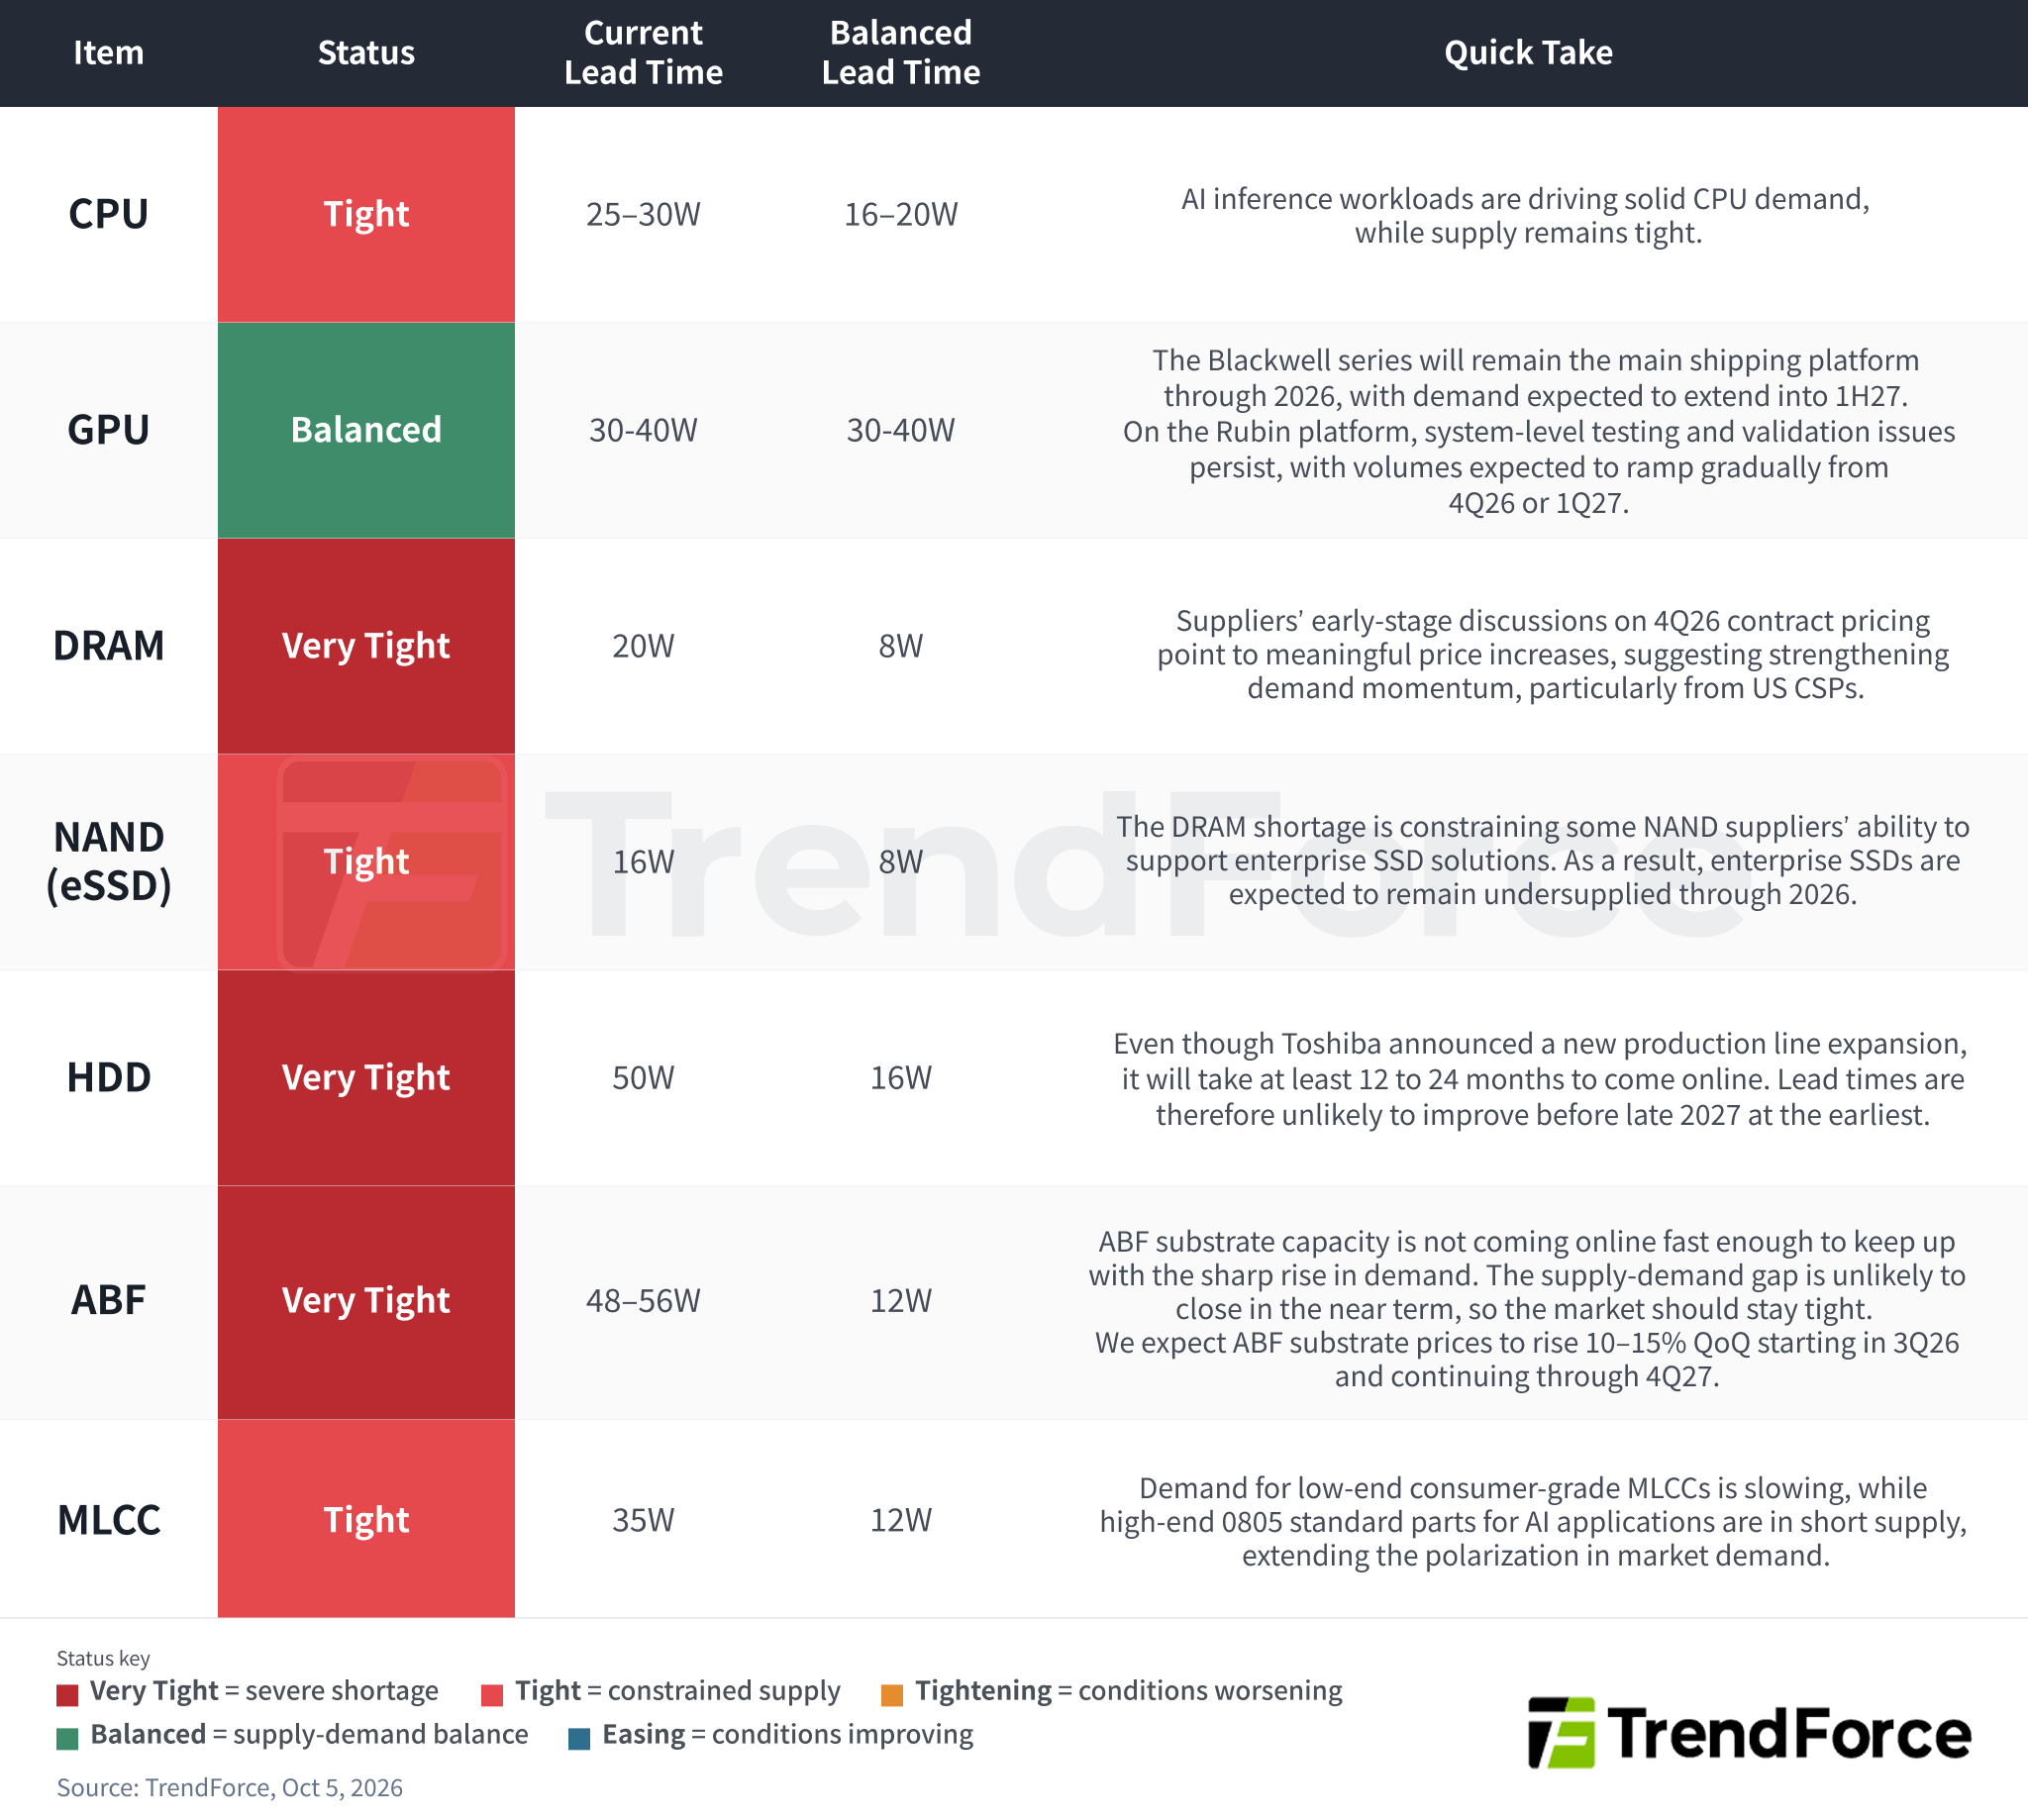
Memory supply remains tight with no clear sign of relief. DRAM remains Very Tight at 20 weeks versus an 8-week balanced level, while shortages are limiting some NAND suppliers’ ability to support enterprise SSD solutions.
Anthropic’s IPO filing puts a number on the AI infrastructure buildout: at least $518 billion. The long-term commitments span cloud computing, equipment and services, with roughly 80% non-cancelable or payable regardless of usage.
Samsung is the next test for the memory upcycle. After Micron’s record quarter, Samsung’s Q3 preliminary results this week will show whether higher memory prices are still translating into earnings momentum, while its HBM4 ramp remains another key watch point.
01 / Supply Chain Radar
We track CPU, GPU, DRAM, NAND, HDD, ABF, and MLCC each week. Start with the status color, then compare the current lead time with the balanced-market benchmark and read the quick take.
02 / Last Week in Tech: Top 3 Industry Shifts
SEMICONDUCTORS / MEMORY
Micron Posts Record $54.2B Quarter, Sees No End to Memory Tightness
What Happened: Micron posted FQ4 revenue of $54.2 billion, up 31% QoQ, with non-GAAP gross margin reaching a record 87%, and guided FQ1 revenue to $61.5 billion. However, with contract prices rising from an already high base, sequential DRAM ASP growth eased to the high-teens percentage range. Meanwhile, Micron added 10 strategic customer agreements (SCAs), bringing its total to 26, some extending to 2031. These SCAs are expected to account for over 35% of revenue through 2030, underscoring the company’s decisive pivot toward long-term contracts.
Why It Matters: Management said it has no line of sight to when supply and demand will return to balance, projecting DRAM and NAND bit shipments to grow only in the low-20% and mid-20% ranges, respectively, through 2027–2028—with both markets still supply constrained. TrendForce believes the supply bottleneck remains structural amid AI-driven demand: cleanroom shortages, rising HBM trade ratios and diminishing gains from node transitions continue to constrain output. With more than 75% of Micron’s 2027 output already committed, supply is expected to remain tight in the year ahead.
AI / SEMICONDUCTOR
Anthropic Eyes $2T IPO as $518B Infrastructure Bill Ripples Through the Supply Chain
What Happened: Anthropic is preparing an IPO at a valuation of up to $2 trillion, with marketing now expected to begin the week of Nov 9 and a listing targeted before Thanksgiving (Nov 26)—later than the October timeline initially reported. Its filing shows 2025 revenue of about $4.6 billion, nearly 12 times 2024’s $386 million, alongside a net loss of roughly $42 billion, more than $34 billion of which stems from fair-value changes on debt rather than core operations.
Why It Matters: The filing puts a price tag on the AI buildout: Anthropic has committed at least $518 billion to infrastructure over the next decade, about 80% of it non-cancelable. The largest line is $161.2 billion in equipment leases with Broadcom, followed by Google ($111.1B), Amazon ($110B), xAI capacity ($84.5B), Microsoft ($31.4B) and AMD (over $20B), with Micron, Samsung and SK hynix named as memory partners.
AI / POLICY
Trump, AI Chiefs Sign Voluntary “Super Intelligence” Accord
What Happened: President Trump hosted a who’s who of tech leaders at the White House on Sep 29, where Meta, Nvidia, Google, OpenAI, xAI and Anthropic signed the “White House Accord on Super Intelligence: Joint Commitment on Frontier Responsibilities.” The roughly 300-word pact commits signatories to four layers of safeguards: internal controls that monitor model capabilities in areas such as cybersecurity and biosecurity, dedicated internal oversight teams, independent external auditors, and independent board committees to review their findings. Trump also announced plans for a 10-person AI safety committee and later named Jay Clayton to lead the new Super Intelligence Force.
Why It Matters: The accord is the administration’s clearest signal yet that it favors industry self-regulation over binding rules: Trump called it “morally binding,” but it carries no penalties, no requirement to disclose audit results and no government enforcement—even though OpenAI and Anthropic have publicly called for mandatory national safety standards. For now, that keeps compliance costs light and leaves the compute race untouched, as the text says nothing about chips, data centers, energy or export controls. But the document itself notes the steps may eventually be codified into law, and with Anthropic heading toward its IPO, independent audits and board-level safety committees could quickly become the governance baseline investors expect from every frontier lab.
03 / Week Ahead: Key Events to Watch
WED. OCT 7|FOMC Minutes
Event: The Fed releases minutes from its Sep 15–16 meeting, where it raised rates by 25bp to 3.75%–4.00%, its first move after a five-meeting pause.
Why It Matters: The unanimous hike, paired with a hawkish dot plot pointing to a 4.1% year-end median, revived talk of a new tightening cycle. Since then, softer August core PCE (3.0%) and New York Fed President John Williams’ “no need for urgency” remarks have pushed markets toward a hold on Oct 28. The minutes will show which camp has the upper hand ahead of the Oct 14 CPI print.
Key Watch Points: One-and-Done or a New Cycle, Oil vs. Jobs:
Watch how many officials see another hike as necessary this year, and how much weight the Committee puts on rising oil prices versus cooling labor demand.
WED. OCT 7|Applied Digital Reports Fiscal Q1 Earnings
Event: Applied Digital is scheduled to discuss its fiscal Q1 2027 results on October 7, with a conference call at 5:00 p.m. ET.
Why It Matters: Applied Digital has become a bellwether for the AI data-center buildout, with 1.4 GW of contracted critical IT load and approximately $36 billion in contracted base-term lease revenue as of its FY2026 year-end. Its results may offer an early read on whether AI demand is translating into energized capacity on schedule.
Key Watch Points: Leasing, Power and Financing:
Watch for new hyperscaler leases, the ramp at Polaris Forge 1, and progress on the 1.2 GW generation project being developed through Base Electron. Applied Digital reported $5.0 billion in debt and $4.2 billion in cash, cash equivalents and restricted cash as of May 31, 2026, making financing costs another key item to watch.
THU. OCT 8|Samsung Reports Q3 Preliminary Earnings
Event: Samsung Electronics is expected to release preliminary Q3 results, with the latest FnGuide consensus at KRW 108.1 trillion in operating profit and KRW 201.7 trillion in revenue.
Why It Matters: Samsung is on track to top KRW 100 trillion in quarterly operating profit for the first time, up from KRW 89.5 trillion in Q2. Following Micron’s record quarterly revenue and stronger-than-expected outlook, Samsung’s results will offer another read on whether the memory upcycle is continuing—or whether slower price gains are beginning to temper earnings growth.
Key Watch Points: Profit Milestone, Memory Momentum, Currency:
Samsung expects Q3 HBM4 revenue to more than triple quarter on quarter and has begun shipping HBM4E samples. Watch whether higher memory prices are translating into stronger earnings, and how much of the profit growth is coming from Samsung’s memory business.